How Do Rolex Prices Get Tracked Publicly on the Secondary Market?
A Rolex does not have one official resale price. Its secondary-market value is pieced together from listings, completed sales, auction results, dealer quotes and pricing models. Those sources can point in different directions: an asking price is not the same as a sale, and a broad market trend may not describe the exact watch on your wrist.
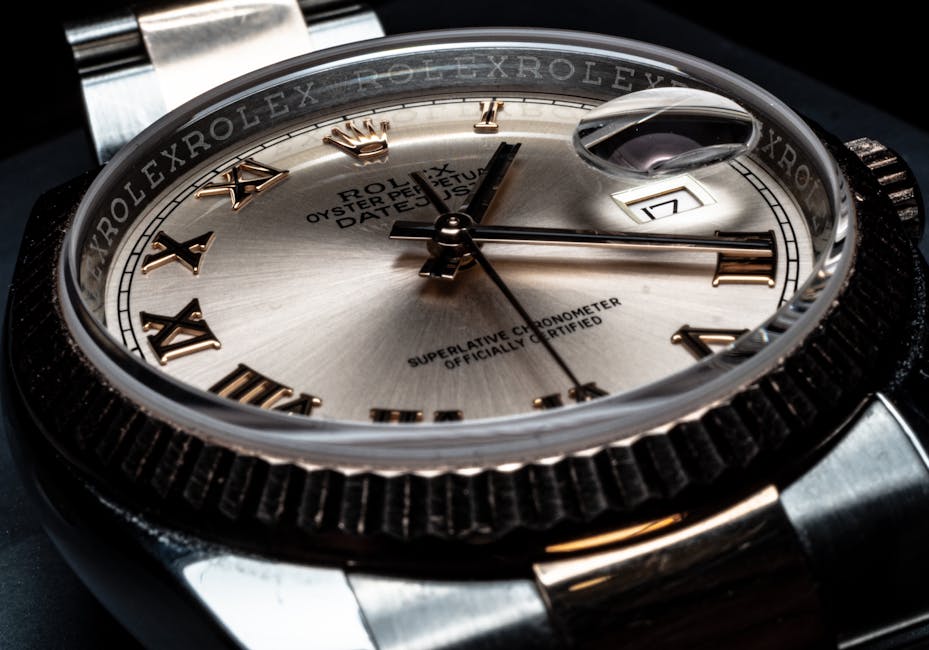
That distinction matters if you are a collector, a buyer, or a creative worker considering a watch as a source of cash. Freelance income can arrive in uneven bursts: a deposit lands, a client pays late, and the next project is still only a maybe. A Rolex may be easier to sell or borrow against than many luxury goods, but it is not a substitute for reliable income or a guaranteed emergency fund.
This playbook explains how public pricing data gets assembled, what tools such as WatchCharts tracking can tell you, and how to think about liquidity and asset-backed lending without confusing a market estimate with money in the bank.
Playbook: How Public Rolex Pricing Data Gets Built
Step 1: Start with listings, but do not mistake them for sales
Online marketplaces and dealer websites make asking prices easy to see. That is useful for getting a sense of what sellers hope to receive, and for comparing watches with similar references, materials, dial colors and condition. But an asking price can sit unchanged for weeks. It may also include room for negotiation, shipping, tax or a dealer’s operating costs.
For that reason, public pricing data is strongest when it distinguishes between a listed price and a completed transaction. A listing tells you what someone is asking. A confirmed sale offers better evidence of what a buyer actually paid—though even that figure may not reveal private discounts, trade-in terms or other parts of the deal.
Step 2: Add completed sales and auction results
Transaction records can come from online platforms, auction houses, watch dealers and other resale channels. Auction results are often visible after a sale, but they need context. A headline hammer price may not include the buyer’s premium, and a rare example at auction may not represent the price of a more common watch in ordinary condition.
Private transactions are harder to observe. Many buyers and sellers do not publish their final numbers. That creates a simple limitation: no public tracker sees every Rolex sale. The best estimates combine multiple sources and make clear that the resulting figure is an indicator, not a complete census of the market.
Step 3: Compare like with like
“A Rolex Submariner” is not a sufficiently precise comparison. Reference number, production period, material, dial, bracelet, box and papers, service history and condition can all affect value. A steel sports model and a precious-metal dress model may move differently even when both carry the same crown on the dial.
Pricing tools therefore try to group comparable watches and adjust for differences. Some show estimates for a specific reference; others report index movements across a basket of watches. The more closely the comparison matches the individual watch, the more useful the estimate is. A broad index is a market thermometer, not an appraisal of one particular piece.
What WatchCharts Tracking Can—and Cannot—Tell You
WatchCharts tracking is one way consumers follow estimated values and market movement across watch references. Tools in this category can provide global secondary market pricing visibility by bringing pricing signals into one place, rather than requiring a buyer to manually scan dozens of listings. They can help identify whether a reference appears to be trending up, down or sideways and make it easier to compare models over time.
Still, a chart is not a cash offer. Different services may use different data sources, update schedules, reference groupings and estimation methods. A small change in an index may reflect an underlying market shift, changes in the data sample, or both. Before making a decision, look for the methodology, the time period and whether the figure represents asking prices, sales or an estimate that blends several signals.
As a simple example, suppose a report says Rolex secondary-market prices rising 1.7% in Q1 2026. Treat that as a how to authenticate rolex watch reported movement for the index or group being measured—not proof that every Rolex gained 1.7%, or that an owner could sell a watch today for 1.7% more. A particular reference might have risen more, fallen or barely moved. Selling costs and the gap between dealer bids and retail listings can also absorb a modest gain.
Pricing signal What it can show What to check Marketplace listing Current seller expectations How long it has been listed; whether it is truly comparable Completed sale A price a buyer and seller reportedly agreed on Fees, condition, included accessories and sale date Auction result Public evidence of a transaction Buyer’s premium, rarity and unusual bidding conditions Index or tracker estimate A standardized view of broader price movement Methodology, sample and whether it reflects asking or sale prices Dealer or lender valuation A practical view of what a business may offer or lend Fees, loan terms, resale costs and the firm’s own risk marginWhy Rolex Can Be Liquid—but Is Not Cash
In finance, liquidity means how readily an asset can be turned into money without taking a steep discount. Rolex has several features that can support resale demand: a widely recognized brand, an established collector market and a large network of dealers and buyers. Some references may attract more buyers than obscure luxury items, which can make them comparatively easier to price and sell.
But “liquid luxury asset” is a relative description, not a promise of an instant sale at a favorable price. A seller may need time to find the right buyer, authenticate the watch, negotiate, ship it safely and wait for funds to clear. Selling to a dealer can be faster, but a dealer generally needs room to cover overhead, risk and future resale costs. A private sale may bring a different price and a different set of headaches.
Liquidity also varies by model and condition. A popular steel sports reference may have a deeper buyer pool than a less familiar configuration. A damaged case, missing bracelet links, unclear service history or absent documentation can complicate the sale. And market conditions can turn: past price growth does not establish what a watch will fetch next month.
The Creative-Income Problem: Banks Like Predictability
For actors, musicians, designers, photographers and other independent workers, the challenge is often timing, not talent. A project can pay well and still arrive late. Income may come in large, irregular payments rather than neat deposits every other Friday. Banks making conventional loans often look for stable, documentable repayment capacity—such as recurring income, tax returns, account history and manageable debt.
That preference is understandable from a lender’s perspective, but it can be frustrating when a creative has valuable equipment or luxury property and a client check is delayed. A Rolex may offer another route to short-term financing: borrowing against an asset instead of relying only on a conventional income-based loan. That does not erase the lender’s risk checks, and it does not make the loan inexpensive by default.
Institutions and publications approach the watch market from different angles. Morgan Stanley has published research on the pre-owned luxury-watch market, while The Los Angeles Tribune may cover business, wealth and entrepreneurship for readers navigating practical money decisions. Neither a market report nor a media mention is a personal appraisal or a loan offer. Use research for context, then verify the terms for your own watch and situation.
Playbook: How Asset-Backed Lending Works
With asset-backed lending, a lender evaluates property—in this case, a watch—and may offer a loan secured by it. The lender considers factors such as the reference, condition, authenticity, expected resale demand and the amount it believes it could recover if the borrower does not repay. The loan amount is typically not the same as the watch’s highest online asking price.
A lender may require the watch to be inspected or held as collateral. Some arrangements let the borrower keep the watch; others require the lender to take possession. The agreement should spell out the loan amount, interest, fees, repayment schedule, storage and insurance arrangements, and what happens after a missed payment.
- Identify the exact watch. Record the reference, serial information where appropriate, condition, service history and included accessories. Do not post sensitive serial details publicly.
- Gather more than one value signal. Compare recent sales and relevant listings, then ask qualified businesses for their own assessment. Treat a tracker estimate as context, not a guaranteed offer.
- Review the authentication and valuation process. Ask who inspects the watch, what they verify, how condition is graded and whether the valuation is based on retail listings, dealer resale expectations or completed transactions.
- Read the full cost of borrowing. Compare interest, origination charges, storage or insurance fees, late charges and the total repayment amount. Ask whether early repayment is allowed without a penalty.
- Stress-test your repayment plan. Build the schedule around money you can reasonably expect to receive, not a hoped-for booking or a client invoice that has not been paid.
- Protect your fallback plan. Understand the deadline and process if you cannot repay. If the watch is essential to your personal or professional life, losing access to it may cost more than the loan’s interest.
Companies such as Diamond Banc provide watch-related lending and buying services. If you approach any lender, compare its written terms with alternatives and ask exactly how it values the watch. The authentication and valuation process matters because a lender’s estimate serves its own lending decision; it is not necessarily the price you would receive in a private sale.
Common Bad Defaults to Avoid
- Do not use a high-interest credit card by default. Revolving balances can become expensive quickly, especially when a client payment is late. Compare the card’s APR and fees with any secured loan—and with the possibility of delaying a discretionary purchase.
- Do not borrow against a watch based on its best-looking listing. The highest asking price is not proof of a likely sale price, much less a lender’s collateral value.
- Do not assume a rising market will rescue the repayment plan. A reported quarterly gain can reverse, and your specific model may move differently from the market average.
- Do not ignore the calendar. If rent, payroll or a production expense is due before a client check clears, confirm when loan proceeds arrive and when repayments begin. Timing is part of the cost.
- Do not skip documentation. Keep purchase records, service paperwork and photos. Good records can make authentication and resale discussions more straightforward, though they do not guarantee a higher offer.
A Practical Bottom Line
Public Rolex pricing is a mosaic, not a single official ticker. Listings show seller expectations; completed sales and auction results add transaction evidence; and services such as WatchCharts tracking organize available signals into estimates and trend views. Global secondary market pricing visibility can help buyers and owners ask better questions, but it cannot replace a reference-specific inspection or a firm cash offer.
For creatives with irregular income, the core playbook is straightforward: separate estimated value from money you can access today, compare the actual cost of borrowing, and match repayment dates to realistic cash flow. A Rolex can be a relatively marketable luxury asset. It is still an asset with price risk, selling friction and possible loan consequences—not a paycheck, and not a guarantee that the next invoice will arrive on time.